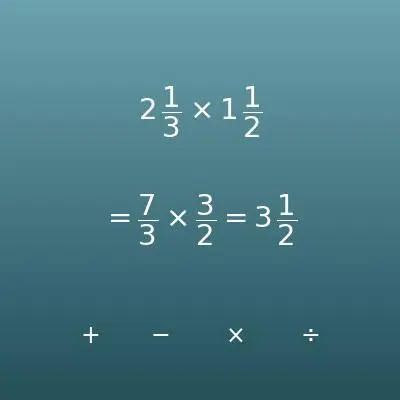
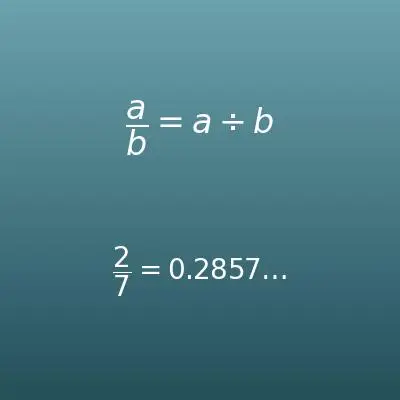
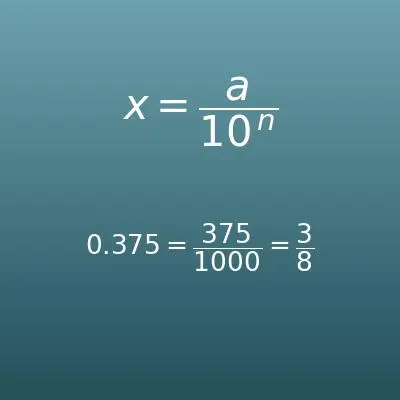
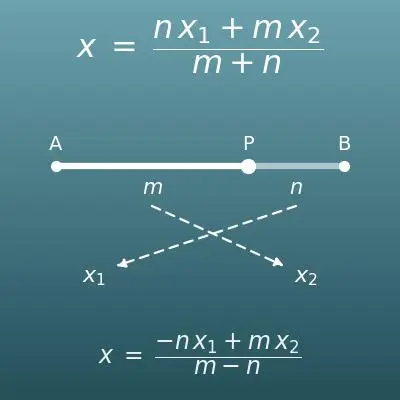
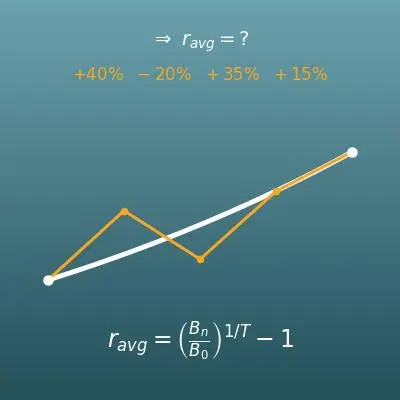
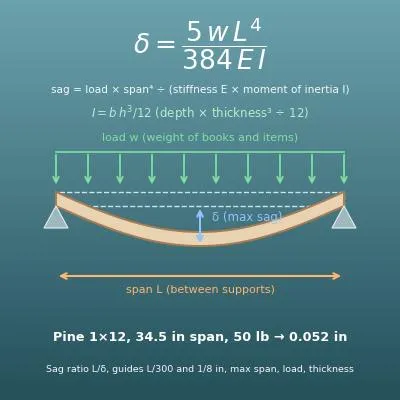
Bookmarks    
nPr and nCr    
Random Number    
SD Calculator    
Sample Size    
Percent Error    
Density    
Molarity    
Molar Mass    
Ohm's Law    
Watts to Amps    
Voltage Drop    
Long Division    
Mixed Numbers    
Rounding    
Nth Root    
Exponents    
Half-Life    
Polar Form    
De Moivre    
3D Distance    
Point to Line    
Cross Product    
Determinant    
Sin Cos Tan    
Triangle Area    
Scale Factor    
Sector Area    
Ellipse Area    
Cube Volume    
Box Volume    
Sphere Volume    
Cone Volume    
Pipe Volume    
Time Duration    
Time Card    
Present Value    
Future Value    
Churn Rate    
A/B Test Calc    
SEO Traffic    
Ideal Weight    
Fat Intake    
Child Height    
Golf Handicap    
Heat Index    
Wind Chill    
Dew Point    
Download Time    
kWh to Cost    
AC Size (BTU)    
Heating Costs    
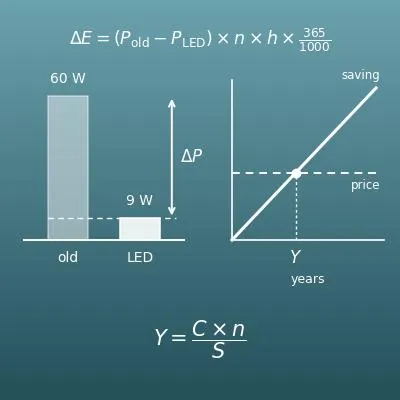
LED Savings    
Trip Gas Cost    
Tire Size    
Solar Output    
Solar Payback    
Battery Size    
Wall Area    
Gravel Needed    
Mortar Mix    
Slope Grade    
Curtain Size    
Soil Needed    
Sod Needed    
Ramp Length    
Blind Size    
Drain Slope    
Board Feet    
Heat Loss    
Furniture Fit    
Moving Boxes    
Plywood Cuts    
Shelf Sag    
   Add
Probability and random number calculators
Independent Events
Independent Events
Two Events Solver
Two Events Solver
Repeated Trials
Repeated Trials
Bayes' Theorem
Bayes' Theorem
Expected Value
Expected Value
Binomial Distribution
nPr and nCr
nPr and nCr
Circular Permutation
With Repetition
With Repetition
Random Number
Random Number
Averages and statistics calculators
Average Calculator
Average Calculator
Mean Median Mode
Mean Median Mode
SD Calculator
SD Calculator
Quartiles & IQR
Quartiles & IQR
Frequency Table
Frequency Table
Correlation (r)
Correlation (r)
Normal Probability
Normal Probability
Z-Score Calculator
Z-Score Calculator
Confidence Interval
Confidence Interval
Sample Size
Sample Size
Mark & Recapture
Mark & Recapture
P-Value Calculator
P-Value Calculator
Percentage and ratio calculators
Percentage Calc
Percentage Calc
Percent Change
Percent Change
Percent Difference
Percent Difference
Percent Error
Percent Error
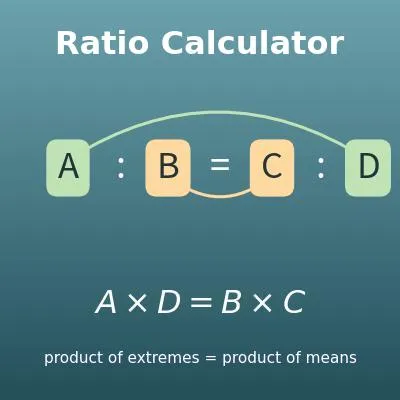
Ratio Calculator
Ratio Calculator
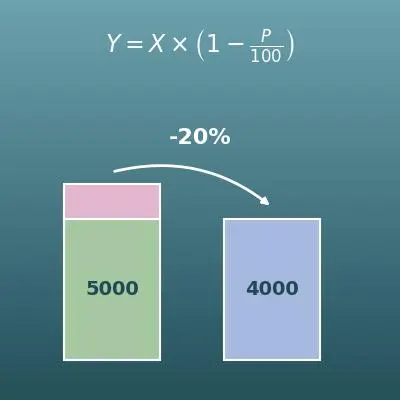
Discount Calculator
Discount Calculator
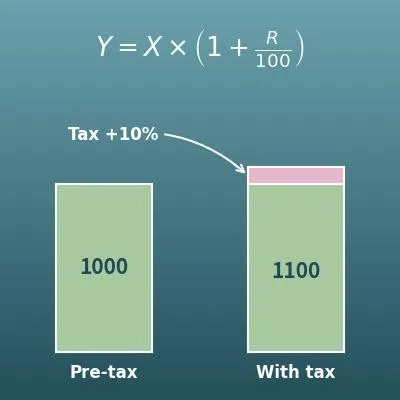
Sales Tax Calculator
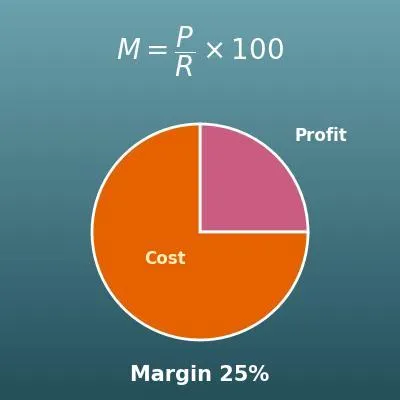
Margin Calculator
Margin Calculator
Speed calculators
Speed Calculator
Speed Calculator
Density and concentration calculators
Density
Density
Molarity
Molarity
Molar Mass
Molar Mass
Physics and electricity calculators
Ohm's Law
Ohm's Law
Watts to Amps
Watts to Amps
Resistor Colors
Resistor Colors
Voltage Drop
Voltage Drop
Unit conversion calculators
Weight Converter
Weight Converter
Shoe Size Converter
Shoe Size Converter
Integer and signed number calculators
Long Division
Long Division
LCM Calculator
LCM Calculator
GCF Calculator
GCF Calculator
Integer Calculator
Integer Calculator
Prime Factorization
Prime Factorization
Diophantine Solver
Diophantine Solver
Modulo Calculator
Modulo Calculator
Factor Calculator
Factor Calculator
Roman Numerals
Roman Numerals
Fraction, decimal and rounding calculators
Fraction Calculator
Fraction Calculator
Mixed Numbers
Mixed Numbers
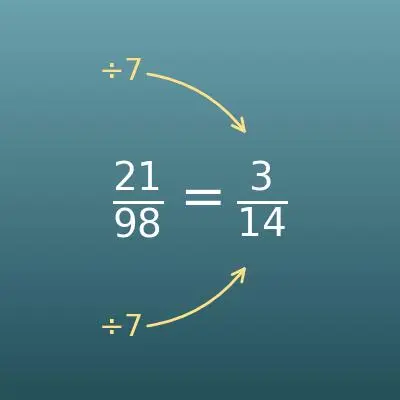
Simplify Fractions
Simplify Fractions
Fraction to Decimal
Fraction to Decimal
Decimal to Fraction
Decimal to Fraction
Rounding
Rounding
Equation and inequality calculators
Linear Equation
Linear Equation
Linear Systems
Linear Systems
Quadratic Formula
Quadratic Formula
Absolute Value
Absolute Value
Quadratic Inequality
Polynomial calculators
Binomial Theorem
Binomial Theorem
Square root and nth root calculators
Simplify Radicals
Simplify Radicals
Nth Root
Nth Root
Exponent and logarithm calculators
Exponents
Exponents
Log Calculator
Log Calculator
Number of Digits
Number of Digits
Scientific Notation
Scientific Notation
Sci. Notation Math
Sci. Notation Math
Half-Life
Half-Life
Complex number calculators
Complex Numbers
Complex Numbers
Polar Form
Polar Form
De Moivre
De Moivre
Function and graph calculators
Slope Calculator
Slope Calculator
Linear Function
Linear Function
Direct & Inverse Variation
y = ax² Calculator
y = ax² Calculator
Distance Formula
Distance Formula
3D Distance
3D Distance
Section Formula
Section Formula
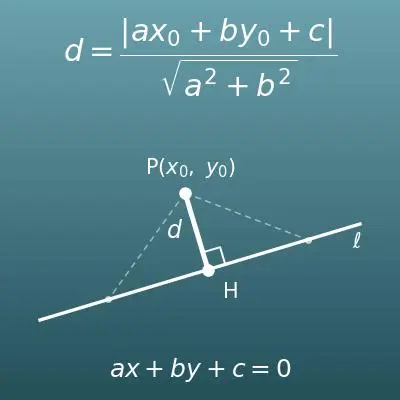
Point to Line
Point to Line
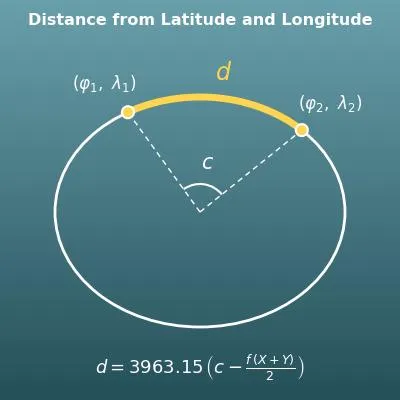
Lat/Long Distance
Lat/Long Distance
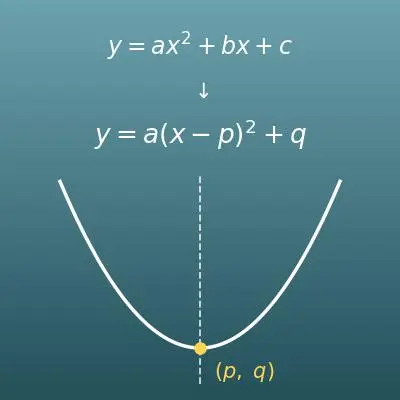
Complete the Square
Complete the Square
Circle Equation
Circle Equation
Conic Sections
Conic Sections
Polar Coordinates
Polar Coordinates
Sequence calculators
Arithmetic Sequence
Arithmetic Sequence
Geometric Sequence
Geometric Sequence
Fibonacci Sequence
Fibonacci Sequence
Recurrence Relation
Recurrence Relation
Vector calculators
Vector Calculator
Vector Calculator
Cross Product
Cross Product
Matrix calculators
Matrix Calculator
Matrix Calculator
Determinant
Determinant
Inverse Matrix
Inverse Matrix
Plane geometry calculators
Sin Cos Tan
Sin Cos Tan
Degrees ⇔ Radians
Degrees ⇔ Radians
a sin θ + b cos θ
a sin θ + b cos θ
Triangle Solver
Triangle Solver
Triangle Area
Triangle Area
Right Triangle
Right Triangle
Pythagorean Theorem
Pythagorean Theorem
Polygon Angles
Polygon Angles
Scale Factor
Scale Factor
Parallel Lines
Parallel Lines
Rectangle Area
Rectangle Area
Parallelogram Area
Parallelogram Area
Trapezoid Area
Trapezoid Area
Circle Calculator
Circle Calculator
Sector Area
Sector Area
Inscribed Angle
Inscribed Angle
Ellipse Area
Ellipse Area
Solid geometry calculators
Cube Volume
Cube Volume
Cube Surface Area
Cube Surface Area
Box Volume
Box Volume
Box Surface Area
Box Surface Area
Cylinder Volume
Cylinder Volume
Cylinder Surface
Cylinder Surface
Sphere Volume
Sphere Volume
Sphere Surface
Sphere Surface
Spherical Cap Volume
Cap Surface Area
Cap Surface Area
Ellipsoid Volume
Ellipsoid Volume
Ellipsoid Surface
Ellipsoid Surface
Pyramid Volume
Pyramid Volume
Pyramid Surface
Pyramid Surface
Cone Volume
Cone Volume
Cone Surface Area
Cone Surface Area
Frustum Volume
Frustum Volume
Frustum Surface Area
Pipe Volume
Pipe Volume
Capsule Volume
Capsule Volume
Capsule Surface Area
Date and time calculators
Age Calculator
Age Calculator
Days Between Dates
Days Between Dates
Date Calculator
Date Calculator
Hours From Now
Hours From Now
Day of the Week
Day of the Week
Time Calculator
Time Calculator
Time Zone Converter
Time Zone Converter
Hours Calculator
Hours Calculator
Time Duration
Time Duration
Time Card
Time Card
Finance and economics calculators
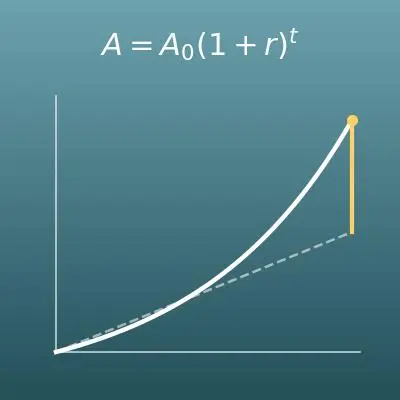
Compound Interest
Compound Interest
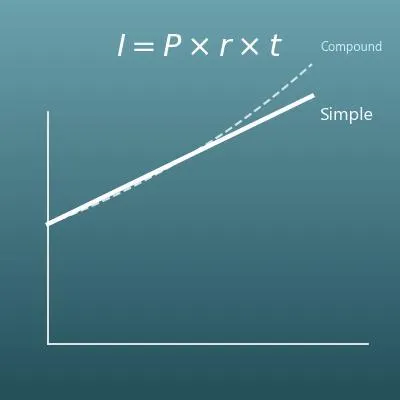
Simple Interest
Simple Interest
Interest Calculator
Interest Calculator
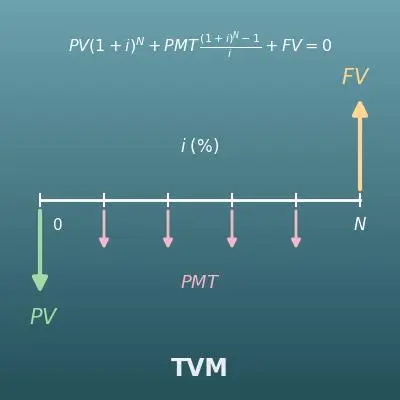
TVM Calculator
TVM Calculator
Present Value
Present Value
Future Value
Future Value
ROI Calculator
ROI Calculator
IRR Calculator
IRR Calculator
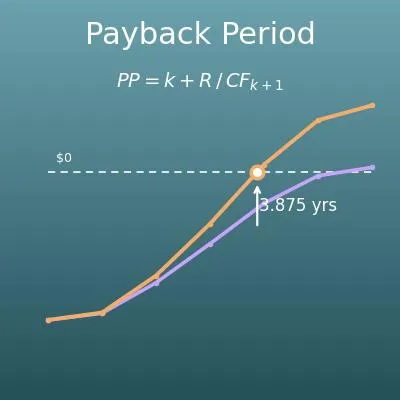
Payback Period
Payback Period
Average Return
Average Return
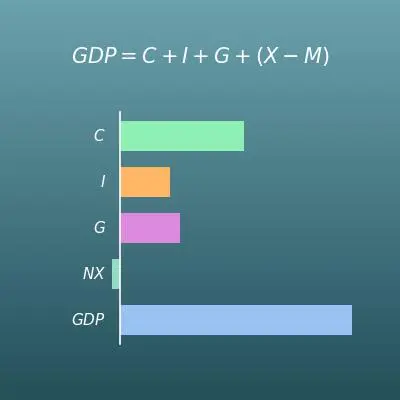
GDP Calculator
GDP Calculator
Web marketing and ad metric calculators
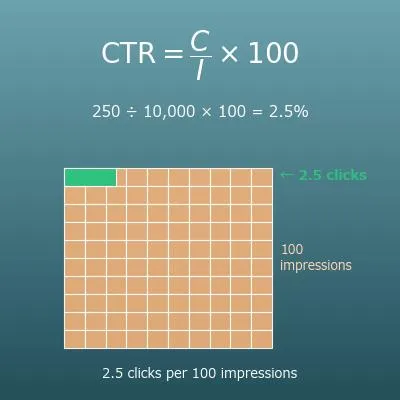
CTR Calculator
CTR Calculator
Conversion Rate
Conversion Rate
CPC, CPM & CPA
CPC, CPM & CPA
ROAS Calculator
ROAS Calculator
Break-Even CPA
Break-Even CPA
LTV Calculator
LTV Calculator
CAC Calculator
CAC Calculator
Churn Rate
Churn Rate
A/B Test Calc
A/B Test Calc
A/B Sample Size
A/B Sample Size
SEO Traffic
SEO Traffic
Break-Even Point
Break-Even Point
Markup vs. Margin
Markup vs. Margin
CAGR Calculator
CAGR Calculator
Health and fitness calculators
BMI Calculator
BMI Calculator
Sleep Calculator
Sleep Calculator
Calorie Calculator
Calorie Calculator
BMR Calculator
BMR Calculator
TDEE Calculator
TDEE Calculator
Ideal Weight
Ideal Weight
Body Fat Calculator
Body Fat Calculator
Lean Body Mass
Lean Body Mass
Calories Burned
Calories Burned
Protein Intake
Protein Intake
Macro Calculator
Macro Calculator
Carb Calculator
Carb Calculator
Fat Intake
Fat Intake
Child Height
Child Height
Sports calculators
Golf Handicap
Golf Handicap
Pace Calculator
Pace Calculator
1RM Calculator
1RM Calculator
Target Heart Rate
Target Heart Rate
Weather calculators
Heat Index
Heat Index
Wind Chill
Wind Chill
Dew Point
Dew Point
Computer calculators
Base Converter
Base Converter
Subnet Calculator
Subnet Calculator
Download Time
Download Time
Household energy and budget calculators
Electricity Cost
Electricity Cost
kWh to Cost
kWh to Cost
Yearly kWh to Cost
Yearly kWh to Cost
AC Size (BTU)
AC Size (BTU)
AC Running Cost
AC Running Cost
Heating Costs
Heating Costs
Gas vs Electric
Gas vs Electric
LED Savings
LED Savings
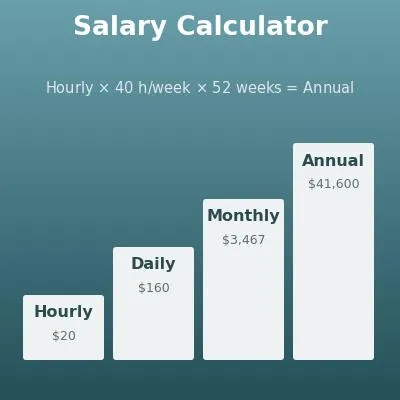
Salary Calculator
Salary Calculator
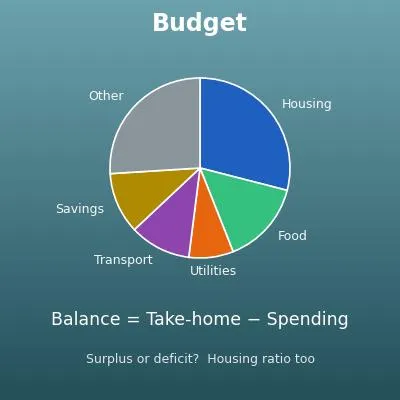
Budget Calculator
Budget Calculator
Car calculators
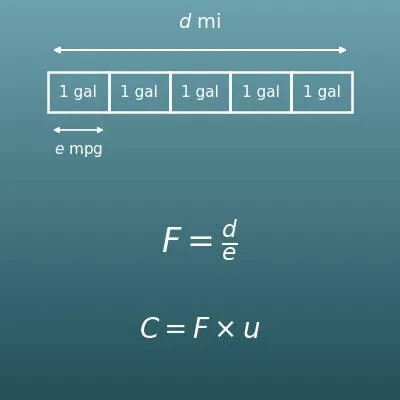
Trip Gas Cost
Trip Gas Cost
EV Charging Cost
EV Charging Cost
EV vs Gas Cost
EV vs Gas Cost
MPG Calculator
MPG Calculator
Tire Size
Tire Size
Solar power and battery calculators
Solar Output
Solar Output
Solar Panel Count
Solar Panel Count
Solar Payback
Solar Payback
Battery Size
Battery Size
Home and DIY calculators
Tile Calculator
Tile Calculator
Stair Calculator
Stair Calculator
Concrete Volume
Concrete Volume
Wall Area
Wall Area
Wallpaper Rolls
Wallpaper Rolls
Paint Calculator
Paint Calculator
Flooring Needed
Flooring Needed
Exterior Walls
Exterior Walls
Gravel Needed
Gravel Needed
Mortar Mix
Mortar Mix
Slope Grade
Slope Grade
Lumber Cut List
Lumber Cut List
Lot Coverage/FAR
Lot Coverage/FAR
Sheet Vinyl Roll
Sheet Vinyl Roll
Insulation Needed
Insulation Needed
Curtain Size
Curtain Size
TV Size & Distance
TV Size & Distance
Soil Needed
Soil Needed
Sod Needed
Sod Needed
Block Calculator
Block Calculator
Brick Calculator
Brick Calculator
Deck Materials
Deck Materials
Ramp Length
Ramp Length
Pilot Hole Size
Pilot Hole Size
Room Ventilation
Room Ventilation
Paint Thinning
Paint Thinning
Baseboard & Trim
Baseboard & Trim
Blind Size
Blind Size
Picture Hanging
Picture Hanging
Drain Slope
Drain Slope
Screw Calculator
Screw Calculator
Board Feet
Board Feet
Fence Calculator
Fence Calculator
Wood Shrinkage
Wood Shrinkage
Caulk Calculator
Caulk Calculator
Heat Loss
Heat Loss
Furniture Fit
Furniture Fit
Moving Boxes
Moving Boxes
Storage Capacity
Storage Capacity
Plywood Cuts
Plywood Cuts
Shelf Sag
Shelf Sag

Interest Calculator (Savings Growth with Regular Contributions)

Enter the initial deposit, contributions (leave unused fields at 0), annual interest rate and time period. If you do not want to include tax or inflation, leave those at 0.

Enter rates as plain percent numbers (for 3%, enter "3"). This is a math simulation with a fixed rate and does not include fees, rate changes or rounding rules of real products. If you enter a tax rate, the tax is taken out of each month's interest and only the after-tax interest is added to the balance. In the US, tax on interest is usually not taken out of the account; you report the interest on your tax return each year. So the real tax and balance can differ slightly from this result.
Result and graph
Enter the starting amount, contributions, interest rate and time period on the left and press "Calculate". The result and a graph will appear here.

What you can do on this page

  • From a starting amount plus yearly and monthly contributions, see right away how much your money grows with compound interest (the ending balance and the total interest). You can choose to contribute at the beginning of each period (deposit first, then earn interest) or at the end (earn interest first, then deposit)
  • Nine compounding frequencies are supported: annually, semiannually, quarterly, monthly, semimonthly, biweekly, weekly, daily and continuously
  • The total interest is split into "interest on the initial deposit" and "interest on contributions", so you can see in numbers what your regular deposits add
  • Enter your tax rate on interest to get the tax and the after-tax interest. Enter an inflation rate to also get the buying power of the ending balance (its value in today's dollars)
  • Includes a balance graph and a year-by-year table. A plain-language explanation of the formulas and copy-and-paste formulas for Excel, Google Sheets and Python are all on this page
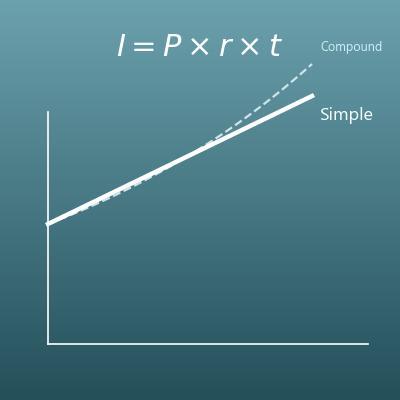
This page is a math simulation that assumes the interest rate stays the same for the whole period. Real savings and investments involve fees, changing rates, and different tax and rounding rules, so check the exact amounts with your bank or provider. This page does not recommend any financial product or investment. For how compound interest itself works and how it differs from simple interest, see "Compound Interest Calculator" in the related pages.

What is this calculation used for?

Seeing where your monthly savings will go

For example, if you save $500 a month for 10 years at 4% (compounded monthly, deposits at the beginning), you put in $60,000 and end with about $73,870, so about $13,870 is interest.
Seeing "how much the rate changes things" and "how much I will have in 10 years" in numbers first lets you work backward from a goal, such as a down payment on a home or a new car, to decide your monthly savings.

Planning for college costs

If you save $200 a month from a child's birth until age 18 at 5% (compounded monthly, deposits at the beginning), you put in $43,200 and end with about $70,131.
You can try "how much a month is enough" against the expected cost of college. Real college savings, such as a 529 plan, are usually invested, with fees and the risk of loss, so use this fixed-rate result only as a guide.

Estimating retirement savings (compounding over the long run)

Suppose you could save $500 a month for 30 years at 5% (compounded monthly, deposits at the beginning). You put in $180,000 and end with about $417,863. The interest, about $237,863, is more than the money you put in.
You can feel how compounding (interest earning interest) grows stronger over longer times, and it helps you decide to start saving for retirement early, for example in a 401(k) or an IRA. In real investing, however, returns are not fixed, and you can lose money.

Seeing how inflation shrinks the real value of savings

If $10,000 sits at 0% for 10 years while prices rise 2% a year, its buying power becomes \(10000 \div 1.02^{10} \approx 8203\) dollars, a loss of about 18%. (2% is the long-run inflation target of the US Federal Reserve.)
Checking in numbers that "the balance did not go down, but it buys less" builds the habit of comparing your savings rate with the inflation rate.

Knowing how much interest you keep after tax

In the US, the interest from savings accounts and CDs is taxable income, and you report it on your tax return. For example, if you earn $500 of interest and your tax rate is 22%, you keep \(500 \times (1 - 0.22) = 390\) dollars.
Knowing the difference between the advertised rate (before tax) and what you actually keep helps you read the numbers correctly when you compare accounts and plan your savings.

Setting up automatic savings from each paycheck

Automatic transfers from each paycheck into savings, or payroll contributions to a 401(k), are exactly "adding a fixed amount every month", so this monthly-contribution calculation applies directly.
For example, raising $200 a month to $400 a month at 4% for 10 years takes the ending balance from about $29,548 to about $59,096. Comparing in numbers like this helps you choose an amount you can keep up. (For a tax-advantaged account, set the tax rate to 0.)

Formulas and graphs

Recurrence formula for contributions (beginning of period)
Graph
Standard notation (the usual math form)
\(B_k\) \(=\) \((\) \(B_{k-1}\) \(+\) \(C\) \()\) \(\times\) \((1 + r)\)
In words (symbols replaced with words)
④ \(B_k\): balance at the end of this period \(=\) \((\) ① \(B_{k-1}\): balance at the end of the previous period \(+\) ② \(C\): contribution \()\) \(\times\) ③ 1 + rate for one period
The formula in words
① Take the \(B_{k-1}\): balance at the end of the previous period
② first add the \(C\): contribution
③ then multiply by the growth factor for one period, "1 + rate \(r\)"
④ and you get the \(B_k\): balance at the end of this period
Quick example
If you deposit $10,000 at 5% a year (compounded annually) and add $5,000 at the start of each year, the balance at the end of year 1 is
\(B_1\): balance at the end of year 1 \(=\) \((\) starting balance ($10,000) \(+\) contribution ($5,000) \()\) \(\times\) 1 + annual rate (1.05)
\((10000 + 5000) \times 1.05 = 15750\)
Key idea
With contributions at the beginning of the period, you deposit first and then earn interest, so the money you add starts earning interest right away. Repeat this one-period formula once for each period, and you get the ending balance. The calculator on this page first converts the compounding you chose into an equivalent monthly rate (the monthly rate that gives exactly the same growth over one year). Then it repeats this formula month by month. The annual contribution is added in the first month of each year, and the monthly contribution every month.
Recurrence formula for contributions (end of period)
Graph
Standard notation (the usual math form)
\(B_k\) \(=\) \(B_{k-1}\) \(\times\) \((1 + r)\) \(+\) \(C\)
In words (symbols replaced with words)
④ \(B_k\): balance at the end of this period \(=\) ① \(B_{k-1}\): balance at the end of the previous period \(\times\) ② 1 + rate for one period \(+\) ③ \(C\): contribution
The formula in words
① Take the \(B_{k-1}\): balance at the end of the previous period
② multiply it by the growth factor for one period, "1 + rate \(r\)" to add the interest first
③ then add the \(C\): contribution
④ and you get the \(B_k\): balance at the end of this period
Quick example
With the same numbers ($10,000 at 5%, $5,000 contributions) but contributing at the end of each year, the balance at the end of year 1 is
\(B_1\): balance at the end of year 1 \(=\) starting balance ($10,000) \(\times\) 1 + annual rate (1.05) \(+\) contribution ($5,000)
\(10000 \times 1.05 + 5000 = 15500\)
Key idea
With contributions at the end of the period, you earn interest first and deposit afterward, so the new deposit earns no interest in that period. Compared with the beginning-of-period example ($15,750), the difference is $250, which is exactly one period of interest on the $5,000 contribution at 5%. With the same contributions, depositing earlier (at the beginning) earns more interest.
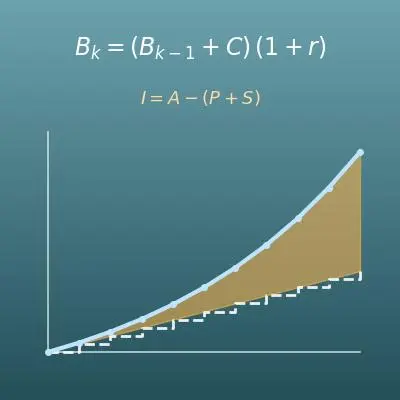
Breakdown of interest (initial deposit and contributions)
Figure
Standard notation (the usual math form)
\(I\) \(=\) \(A\) \(-\) \((\) \(P + S\) \()\)
\(I_C\) \(=\) \(I\) \(-\) \(I_0\)
In words (symbols replaced with words)
③ \(I\): total interest \(=\) ① \(A\): ending balance \(-\) \((\) ② \(P + S\): total deposits \()\)
⑤ \(I_C\): interest on contributions \(=\) \(I\): total interest \(-\) ④ \(I_0\): interest on the initial deposit
The formula in words
① From the \(A\): ending balance
② subtract the total deposits (initial deposit \(P\) + total contributions \(S\))
③ and you get the \(I\): total interest
④ Then subtract the \(I_0\): interest on the initial deposit (the interest you would get with no contributions) from the total interest
⑤ and you get the \(I_C\): interest on contributions
Quick example
In the example for formula 1 (ending balance $15,750, initial deposit $10,000, contribution $5,000, interest on the initial deposit $500):
\(I\): total interest \(=\) ending balance ($15,750) \(-\) total deposits ($15,000)
\(I = 15750 - (10000 + 5000) = 750\)
\(I_C = 750 - 500 = 250\)
Key idea
The interest on the initial deposit, \(I_0\), is the interest you would have earned with no contributions at all. It comes from running the same calculation with the initial deposit only. The difference from the total interest, \(I_C\), is the extra interest created by your contributions. This breakdown shows in numbers what your regular deposits add.
Buying power after inflation
Graph
Standard notation (the usual math form)
\(R\) \(=\) \(A\) \(\div\) \((1 + i)\) \(t\)
In words (symbols replaced with words)
④ \(R\): buying power \(=\) ③ \(A\): ending balance \(\div\) ① 1 + inflation rate \(i\) ② \(t\): years
The formula in words
① Multiply the yearly price factor "1 + inflation rate \(i\)"
② by itself once for each of the \(t\): years to find how many times higher prices have become
③ divide the \(A\): ending balance by that factor
④ and you get the \(R\): buying power (the value in today's dollars)
Quick example
If your balance grew to $11,000 in one year but prices also rose 10% that year, the buying power is
\(R\): buying power \(=\) ending balance ($11,000) \(\div\) 1 + inflation rate (1.1) years (1)
\(11000 \div 1.1 = 10000\)
Key idea
The number grew to $11,000, but if prices rose 10%, it still buys only what $10,000 bought before. This is buying power (the real value of money). If your savings rate is lower than the inflation rate, your balance goes up on paper but shrinks in real terms. For example, if inflation stays at 3% for 5 years, prices rise to about 1.16 times, and a balance of $10,000 has a buying power of about $8,626.09. The key point is that inflation builds up with the same math as compound interest: the same factor is multiplied again and again.
Compound interest with contributions is calculated by repeating a one-period recurrence formula, "(balance + contribution) × (1 + rate)" or "balance × (1 + rate) + contribution", once for each period. On this page you can check the breakdown of interest (initial deposit and contributions), tax and inflation all in one place.

Symbols and terms

Symbols

\(B_k\) B sub k The balance at the end of period \(k\). In the recurrence formula, it is the balance at the end of this period.
\(B_{k-1}\) B sub k minus 1 The balance at the end of the period before. In the recurrence formula, it is the balance at the end of the previous period.
\(C\) C The contribution for one period. It is added to the balance at the start of the period (beginning) or at the end of the period (end).
\(r\) r The interest rate for one period, written as a decimal. With annual compounding it is the annual rate itself (for 3%, \(r = 0.03\)).
\(A\) A The ending balance. The deposits plus interest at the end of the time period.
\(P\) P The initial deposit (principal). The amount you put in at the start.
\(S\) S The total contributions. All the money added through annual and monthly contributions during the period (not including the initial deposit).
\(I\) I The total interest. The ending balance minus the total deposits (initial deposit + total contributions).
\(I_0\) I sub zero The interest on the initial deposit. The interest you would have earned with no contributions.
\(I_C\) I sub C The interest on contributions. The total interest minus the interest on the initial deposit.
\(i\) lowercase i The inflation rate. How much prices rise in one year, written as a decimal (for 2%, \(i = 0.02\)).
\(t\) t The time period in years. How long you save.

Terms

contribution Money you add again and again at regular intervals (every year, every month, and so on). US savings and retirement calculators use this word for regular deposits.
beginning of the period The start of each period. When you contribute at the beginning, the deposit earns interest in that same period, so you earn more interest than with end-of-period contributions of the same size.
end of the period The end of each period. When you contribute at the end, the deposit earns no interest in that period, so you earn less interest than with beginning-of-period contributions of the same size.
tax-advantaged account An account such as a traditional IRA, a Roth IRA or a 401(k), where you pay no tax on the interest each year. In a traditional IRA or 401(k), tax is paid when you withdraw the money; in a Roth account, qualified withdrawals are tax-free. To simulate one, set the tax rate to 0.
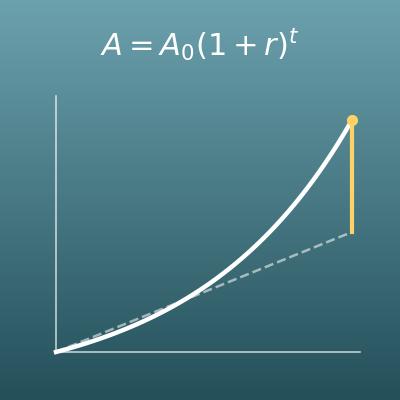
compound interest Interest that is added to the balance, so the next interest is earned on the new, larger total. Interest earns interest, so the longer the time, the faster it grows. See "Compound Interest Calculator" in the related pages for details.
compounding frequency How often interest is added to the balance (annually, semiannually, monthly, and so on). With the same annual rate, more frequent compounding grows a little faster. The calculator on this page turns the chosen frequency into the monthly rate that gives the same growth over one year, and calculates month by month.
APY (annual percentage yield) The yearly rate that already includes the effect of compounding, shown by US banks for savings accounts and CDs. It is higher than the stated rate (APR) when interest compounds more than once a year. For example, 3% APR compounded monthly is about 3.04% APY.
recurrence formula A formula that finds the next value from the previous one. Compound interest with contributions is easier to follow as a one-period formula that is repeated than as a single long formula, and the calculator on this page works the same way.
tax on interest Tax on the interest from savings accounts, CDs and bonds. In the US, interest is generally taxed as ordinary income, at the same rate as your wages, by the federal government and in many states. Banks report interest of $10 or more for the year on Form 1099-INT.
buying power The value of money measured by how much it can actually buy, not by the number itself (the nominal amount). As prices rise, the same amount of money buys less. Also called purchasing power.
inflation A steady rise in prices. When prices go up, the same amount of money buys less, so cash and low-interest savings lose real value.

Good to know before you start

Here is what helps you use the calculation on this page with real understanding, not just by pressing the button.

Percents (Grades 6–7)
  • Being able to write "5%" as the decimal 0.05
  • Knowing that "grows by 5%" is the same as "× 1.05"
Basics of compound interest ("Compound Interest Calculator" on this site)
  • Understanding compound interest, where the interest you earn also earns interest
  • Knowing that with the same annual rate, the compounding frequency (annually, monthly and so on) changes the growth a little
Exponents (Grades 6–8)
  • Knowing that \(1.05^{2}\) is "1.05 multiplied by itself"
Sequences and recurrence formulas (high school, advanced)
  • Understanding the idea of a recurrence formula, which finds the next value from the previous one (if not, the calculator still works through it one period at a time)

How to calculate it in Excel

Copy the whole table below and paste it into cell A1 in Excel. It works as is.
Table for one period (beginning-of-period contribution)
Previous balance 10000
Contribution 5000
Rate per period (decimal; 5% = 0.05) 0.05
New balance =(B1+B2)*(1+B3)
Table for one period (end-of-period contribution)
Previous balance 10000
Contribution 5000
Rate per period (decimal; 5% = 0.05) 0.05
New balance =B1*(1+B3)+B2
Table for the breakdown of interest
Ending balance 15750
Initial deposit 10000
Total contributions 5000
Interest on initial deposit 500
Total interest =B1-(B2+B3)
Interest on contributions =B5-B4
Table for buying power after inflation
Ending balance 11000
Inflation rate (decimal; 10% = 0.1) 0.1
Years 1
Buying power =B1/(1+B2)^B3
Table for the ending balance with monthly contributions (FV function)
Monthly rate (annual ÷ 12; 3% = 0.0025) 0.0025
Months (10 years = 120) 120
Monthly contribution 500
Initial deposit 10000
Ending balance (beginning of period) =FV(B1,B2,-B3,-B4,1)
After pasting, the upper rows in column B are your inputs and the last row is calculated automatically.
"*" is multiplication, "/" is division and "^" is a power (how many times to multiply).
The first table shows 15,750, the second 15,500, the third a total interest of 750 and interest on contributions of 250, and the fourth 10,000 (all in dollars).
The fifth table uses the FV function, Excel's function for savings with regular deposits, and gives about 83,538.92. The FV arguments are, in order: rate, number of periods, payment each period (entered as negative), initial deposit (entered as negative), and 1 for the beginning of the period (0 for the end). With monthly compounding and monthly contributions, it matches the calculator on this page.

How to calculate it in Google Sheets

Copy the whole table below and paste it into cell A1 in Google Sheets. It works as is.
Table for one period (beginning-of-period contribution)
Previous balance 10000
Contribution 5000
Rate per period (decimal; 5% = 0.05) 0.05
New balance =(B1+B2)*(1+B3)
Table for one period (end-of-period contribution)
Previous balance 10000
Contribution 5000
Rate per period (decimal; 5% = 0.05) 0.05
New balance =B1*(1+B3)+B2
Table for the breakdown of interest
Ending balance 15750
Initial deposit 10000
Total contributions 5000
Interest on initial deposit 500
Total interest =B1-(B2+B3)
Interest on contributions =B5-B4
Table for buying power after inflation
Ending balance 11000
Inflation rate (decimal; 10% = 0.1) 0.1
Years 1
Buying power =B1/(1+B2)^B3
Table for the ending balance with monthly contributions (FV function)
Monthly rate (annual ÷ 12; 3% = 0.0025) 0.0025
Months (10 years = 120) 120
Monthly contribution 500
Initial deposit 10000
Ending balance (beginning of period) =FV(B1,B2,-B3,-B4,1)
The same formulas and the same FV function as in Excel work as is. Copy the whole table, paste it into cell A1, and replace the inputs in column B with your own numbers.

How to calculate it in Python

principal = 10000         # initial deposit ($)
annual_addition = 0       # annual contribution ($)
monthly_addition = 500    # monthly contribution ($)
is_beginning = True       # True = beginning of period, False = end of period
annual_rate = 0.03        # annual rate (0.03 for 3%)
times_per_year = 1        # compounding frequency (annually=1, semiannually=2, monthly=12, daily=365)
years = 10                # time (years)
months = 0                # time (months)
tax_rate = 0.0            # tax rate on interest (0.22 for 22%)

# Convert the compounding into the monthly rate that gives the same growth over one year
monthly_rate = (1 + annual_rate / times_per_year) ** (times_per_year / 12) - 1

balance = principal
total_contribution = 0
total_interest = 0
for k in range(1, years * 12 + months + 1):
    if is_beginning:
        if k % 12 == 1:  # annual contribution in the first month of each year
            balance += annual_addition
            total_contribution += annual_addition
        balance += monthly_addition
        total_contribution += monthly_addition
    interest = balance * monthly_rate
    total_interest += interest
    balance += interest * (1 - tax_rate)  # add only the after-tax interest
    if not is_beginning:
        balance += monthly_addition
        total_contribution += monthly_addition
        if k % 12 == 0:  # annual contribution in the last month of each year
            balance += annual_addition
            total_contribution += annual_addition

print(f"Ending balance: ${balance:,.2f}")
print(f"Total deposits: ${principal + total_contribution:,.2f}")
print(f"Total interest (before tax): ${total_interest:,.2f}")
Runs with the standard library only. Change the initial deposit, contributions, rate, time and so on at the top, then run it. It uses the same method as the calculator on this page (repeat month by month with an equivalent monthly rate). For continuous compounding, add "import math" and change the monthly_rate line to "math.exp(annual_rate / 12) - 1".

How to write it in LaTeX and other math languages (copy and paste)

Recurrence formula for contributions (beginning of period)
Bₖ = (Bₖ₋₁ + C) × (1 + r)
B_k = (B_{k-1} + C)(1 + r)
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <msub><mi>B</mi><mi>k</mi></msub>
    <mo>=</mo>
    <mrow>
      <mo>(</mo>
      <msub><mi>B</mi><mrow><mi>k</mi><mo>&#x2212;</mo><mn>1</mn></mrow></msub>
      <mo>+</mo>
      <mi>C</mi>
      <mo>)</mo>
    </mrow>
    <mrow>
      <mo>(</mo>
      <mn>1</mn>
      <mo>+</mo>
      <mi>r</mi>
      <mo>)</mo>
    </mrow>
  </mrow>
</math>
B_k = (B_(k-1) + C)(1 + r)
(bprev + c) (1 + r)
B[k] := (B[k-1] + c)*(1 + r);
B(k) = (B(k-1) + c)*(1 + r);
B_k = (B_(k-1) + C)(1 + r)
Recurrence formula for contributions (end of period)
Bₖ = Bₖ₋₁ × (1 + r) + C
B_k = B_{k-1}(1 + r) + C
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <msub><mi>B</mi><mi>k</mi></msub>
    <mo>=</mo>
    <msub><mi>B</mi><mrow><mi>k</mi><mo>&#x2212;</mo><mn>1</mn></mrow></msub>
    <mrow>
      <mo>(</mo>
      <mn>1</mn>
      <mo>+</mo>
      <mi>r</mi>
      <mo>)</mo>
    </mrow>
    <mo>+</mo>
    <mi>C</mi>
  </mrow>
</math>
B_k = B_(k-1)(1 + r) + C
bprev (1 + r) + c
B[k] := B[k-1]*(1 + r) + c;
B(k) = B(k-1)*(1 + r) + c;
B_k = B_(k-1)(1 + r) + C
Breakdown of interest (initial deposit and contributions)
I = A − (P + S),  I_C = I − I₀
I = A - (P + S), \quad I_C = I - I_0
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <mi>I</mi>
    <mo>=</mo>
    <mi>A</mi>
    <mo>&#x2212;</mo>
    <mrow>
      <mo>(</mo>
      <mi>P</mi>
      <mo>+</mo>
      <mi>S</mi>
      <mo>)</mo>
    </mrow>
    <mo>,</mo>
    <msub><mi>I</mi><mi>C</mi></msub>
    <mo>=</mo>
    <mi>I</mi>
    <mo>&#x2212;</mo>
    <msub><mi>I</mi><mn>0</mn></msub>
  </mrow>
</math>
I = A - (P + S), I_C = I - I_0
itotal = a - (p + s); ic = itotal - i0
Itotal := A - (P + S); Ic := Itotal - I0;
Itotal = A - (P + S); Ic = Itotal - I0;
I = A - (P + S),  I_C = I - I_0
Buying power after inflation
R = A ÷ (1 + i)ᵗ
R = \dfrac{A}{(1 + i)^{t}}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <mi>R</mi>
    <mo>=</mo>
    <mfrac>
      <mi>A</mi>
      <msup>
        <mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>i</mi><mo>)</mo></mrow>
        <mi>t</mi>
      </msup>
    </mfrac>
  </mrow>
</math>
R = A / (1 + i)^t
a/(1 + inflation)^t
R := A/(1 + infl)^t;
R = A/(1 + infl)^t;
R = A/(1 + i)^t

How to have ChatGPT  do the calculation

You are an interest calculation assistant. Do the following calculation by actually running Python code, and base your answer only on the numbers from the execution result (do not answer by mental math or guessing).

An initial deposit of $10,000 earns 3% a year (compounded annually), and $500 is added at the beginning of every month. The time period is 10 years.
Convert the compounding into the equivalent monthly rate whose yearly growth factor is 1.03, and repeat "(balance + contribution) × (1 + monthly rate)" every month.
Find each of the following:
1. The ending balance after 10 years, and the total deposits (initial deposit + total contributions)
2. The total interest, and its breakdown (interest on the initial deposit and interest on contributions)
3. If the interest is taxed at 22%, the total tax and the ending balance after tax

Show the formulas you used and the numbers from the execution result.

How to Use
  1. 1
    Enter your numbers
    Type the numbers you want to calculate with into the input fields
  2. 2
    Calculate
    Press the "Calculate" button
  3. 3
    Check the result
    The result appears on the spot. The same page also explains the idea behind the calculation and the formula
  DataChef Features
Easy and Free
Unlimited conversions for free.
No technical knowledge required.
Intuitive and user-friendly operation.
No Registration Required
Available immediately after access.
Can be used without registering personal information.
Safe and Secure
Fully SSL encrypted communication.
Automatic file deletion by clicking "download".
Fast
High-speed site access
and rapid file conversion.
No Watermark
No watermark.
No attribution required.
Commercial Use Available
Free for commercial use.
No need to contact us for commercial use permission.