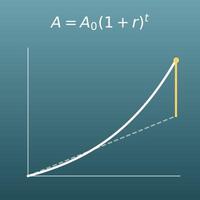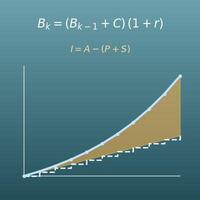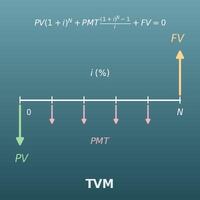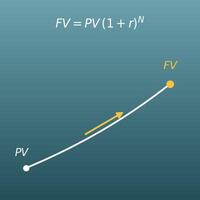
Choose a mode and enter the future amount, the number of periods and the rate. The calculator finds what the future money is worth today (its present value).
Table of Contents
-
What you can do on this page
-
What is this calculation used for?
-
How to Use
-
Formulas and graphs
-
Symbols and terms
-
Good to know before you start
-
How to calculate it in Excel
-
How to calculate it in Google Sheets
-
How to calculate it in Python
-
How to write it in LaTeX and other math languages (copy and paste)
-
How to have ChatGPT do the calculation
-
DataChef Features
-
Related Features
-
NumberChef Calculators List
What you can do on this page
- Enter the amount of money you will receive after \(N\) periods, the number of periods and the rate, and you get what that future money is worth today (the present value \(PV\)) and the amount of the discount (\(FV - PV\))
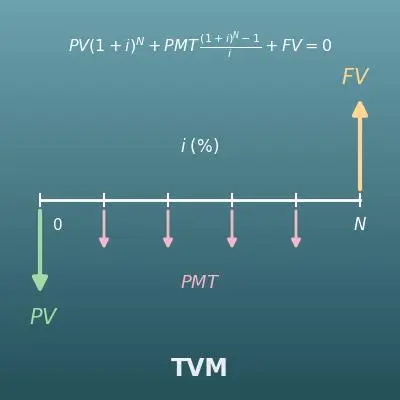
- Switch the mode to find the present value of an annuity, where you receive the same amount every period. Payments at the beginning or end of each period are supported. For reference you also get the future value, the total of payments and the total interest, plus a period-by-period table when the number of periods is a whole number up to 20
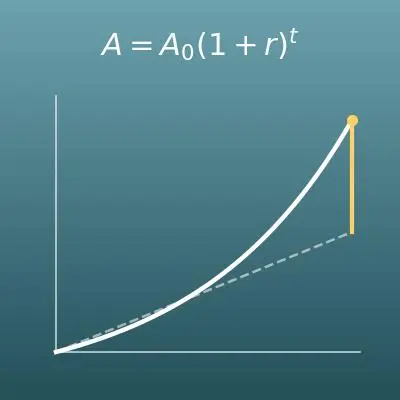
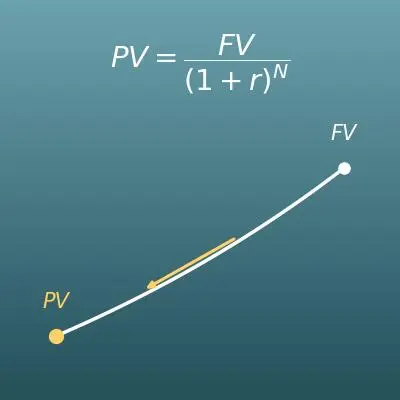
- A graph shows how discounting winds future money back to its value today (save as PNG or SVG)
- All amounts on this page are entered as positive numbers. There is no financial-calculator sign convention (money out is negative), so it is easy even the first time
- A plain-language explanation of the formulas and copy-and-paste formulas for Excel (PV function), Google Sheets and Python are all on this page
What is this calculation used for?
The answer is "$10,000 today". If money can earn 2% a year, the present value of $10,000 in 10 years is \(10000 \div 1.02^{10} \approx 8203.48\) dollars, about $1,797 less than $10,000 today.
Present value turns the feeling that "getting the same amount sooner is better" into a number, based on an assumed rate of return. The return you give up by waiting is called the opportunity cost.
Big US lotteries such as Powerball and Mega Millions let winners choose a lump sum (the cash option, a smaller amount) or an annuity paid over many years (a larger total), and present value is exactly how to compare them. For example, $1 million a year for 20 years ($20 million in total), discounted at 3%, has a present value of about $14.88 million. If the lump sum offered were $15 million, it would be worth slightly more under this assumption.
The conclusion depends on the rate you think you could earn (the assumed discount rate). In practice, you calculate with several discount rates and look for the point where the answer flips (taxes are not included here).
Some employers with a pension plan let retirees choose a one-time lump sum instead of regular pension payments. For example, if you expect $30,000 a year for 20 years ($600,000 in total), discounting at 4% gives a present value of about $407,710. Putting the lump sum offer next to this present value is where the comparison starts.
In a real decision, taxes, how long you expect to live, and what the plan guarantees matter a lot, so this calculation isolates only the time value part. Do not treat it as a final answer; check the rules in your plan documents or with a qualified professional.
A zero-coupon bond pays one amount at maturity and nothing before. A bond that pays $10,000 in 15 years, discounted at 4% a year, has a present value of about $5,552.65. That is roughly the price such a bond would sell for today when similar investments earn 4%.
The same idea shows why bond prices fall when interest rates rise: a higher discount rate makes the same future payment worth less today. This helps when you compare bonds, CDs and other fixed payments in the future.
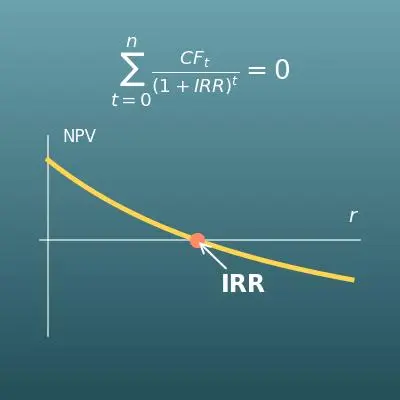
NPV (net present value), the standard method companies use to decide on new equipment or projects, turns each future cash flow, such as sales or costs, into its present value with the formula on this page and adds them all up. If the total is positive, the investment is expected to grow faster than the discount rate.
The same calculation is used in accounting, corporate finance and the cost-benefit analysis of public projects, so discounting is a common language across money-related work.
Formulas and graphs
Symbols and terms
Symbols
| \(PV\) | P V | Present value. What future money is worth in today's money. This is the value this page finds. |
| \(FV\) | F V | Future value. The amount of money you receive at a future time. You enter it in the "Future lump sum" mode; in the annuity mode it is shown for reference. |
| \(PMT\) | payment | The payment each period. The amount you receive (or save) every period. |
| \(N\) | N | The number of periods that earn interest. With yearly payments it equals the number of years: 10 years is \(N = 10\). |
| \(I/Y\) | I over Y | The interest rate per period in % (the name comes from the "interest per year" key on a financial calculator). With yearly payments it is the annual rate itself. |
| \(r\) | r | The interest rate per period as a decimal. For 6%, \(r = 0.06\) (\(I/Y \div 100\)). |
| \((1+r)^N\) | one plus r to the N | How many times money grows in \(N\) periods. At 6% a year for 10 years, it is \(1.06^{10} \approx 1.79\) times. Present value divides by this factor to wind future money back to today. |
| \((1+r)^{-N}\) | one plus r to the negative N | A negative exponent says "divide by \((1+r)^N\)". As in \(1.06^{-10} = 1 \div 1.06^{10}\), it lets you write discounting as a multiplication. |
Terms
| present value | What future money is worth in today's money. For example, if money can earn 2% a year, $10,200 one year from now is worth the same as $10,000 today. |
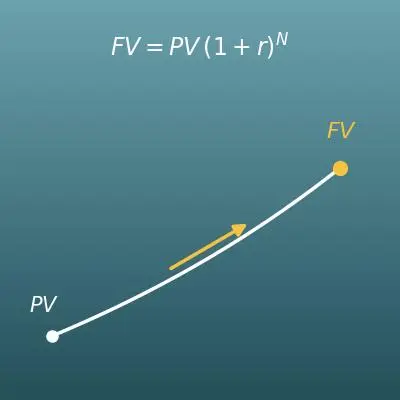
| future value | How much money now, or regular savings, will be worth in the future, including interest. It is the exact counterpart of present value. |
| discounting | Turning future money into its present value. You divide the future amount by \((1+r)^N\), so the value goes down. It is exactly the reverse of growing money with interest (compounding). |
| discount rate | The rate used for discounting; the rate I/Y on this page. It is the rate at which you think the money could grow, and the higher it is, the lower the value today of future money. |
| annuity | In math and finance, a stream of equal payments made every period. Not only pensions and insurance annuities, but also installment payments and regular savings have this form. |
| present value annuity factor | The multiple \(\dfrac{1-(1+r)^{-N}}{r}\): what the right to receive $1 every period is worth today. In engineering economics it is the P/A factor, one of the six standard interest factors. You multiply it by the payment each period. |
| NPV (net present value) | The sum of the present values of all the money in and out, counting money received as plus and money paid as minus. It is used to judge business projects and investments, and the present value of one amount on this page is its building block. |
| opportunity cost | The gain you would have had if you had used the money for something else, such as investing it. Future money is worth less than money today because while you wait, you lose the chance to invest it (you pay an opportunity cost). |
| ordinary annuity | Payments received at the end of each period. Most annuities and savings plans work this way. |
| annuity due | Payments received at the beginning of each period. Each payment arrives one period earlier than in an ordinary annuity, so the present value is \((1+r)\) times larger. |
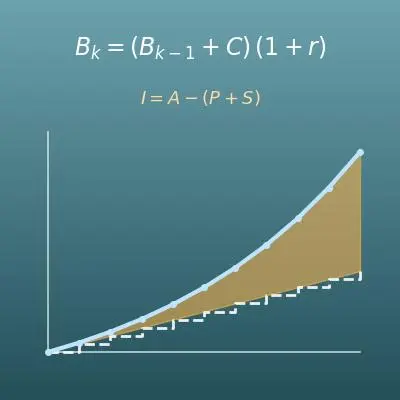
| compound interest | Interest that also earns interest. The present value calculation uses the compound growth factor \((1+r)^N\) on the dividing side. |
Good to know before you start
Here is what helps you use the calculation on this page with real understanding, not just by pressing the button.
| Percents (Grades 6–7) |
|
| Exponents (Grades 6–8) |
|
| Basics of compound interest ("Compound Interest Calculator" on this site) |
|
| Negative exponents (Algebra 1 and 2, advanced) |
|
How to calculate it in Excel
| Rate per period (6% = 0.06) | 0.06 |
| Number of periods N | 10 |
| Future value FV | 1000 |
| Present value PV | =-PV(B1,B2,0,B3) |
| Rate per period (6% = 0.06) | 0.06 |
| Number of periods N | 10 |
| Payment each period PMT | 100 |
| Present value PV | =-PV(B1,B2,B3,0,0) |
| Rate per period (5% = 0.05) | 0.05 |
| Number of periods N | 5 |
| Payment each period PMT | 200 |
| Present value PV | =-PV(B1,B2,B3,0,1) |
The PV function follows the financial-calculator sign convention (if you enter money you receive, the answer is negative), so put a minus sign in front, "=-PV(...)", to get the same positive amount as this page.
The first table shows 558.39 in B4, the second 736.01, and the third 909.19. The last argument is the payment timing: 0 or omitted = end of period, 1 = beginning of period.
How to calculate it in Google Sheets
| Rate per period (6% = 0.06) | 0.06 |
| Number of periods N | 10 |
| Future value FV | 1000 |
| Present value PV | =-PV(B1,B2,0,B3) |
| Rate per period (6% = 0.06) | 0.06 |
| Number of periods N | 10 |
| Payment each period PMT | 100 |
| Present value PV | =-PV(B1,B2,B3,0,0) |
| Rate per period (5% = 0.05) | 0.05 |
| Number of periods N | 5 |
| Payment each period PMT | 200 |
| Present value PV | =-PV(B1,B2,B3,0,1) |
How to calculate it in Python
future_value = 1000       # future value FV (used for the lump sum)
payment = 100             # payment each period PMT (used for the annuity)
periods = 10              # number of periods N
rate_percent = 6          # rate per period I/Y (%)
is_beginning = False      # True = beginning of period, False = end of period (used for the annuity)

r = rate_percent / 100

# Present value of a future lump sum: PV = FV / (1+r)^N
pv_lump = future_value / (1 + r) ** periods
print(f"Present value of the lump sum = {pv_lump:,.2f}")
print(f"Amount of the discount = {future_value - pv_lump:,.2f}")

# Present value of payments each period (annuity). At a 0% rate there is no discount = PMT x N
if r == 0:
    pv_annuity = payment * periods
else:
    pv_annuity = payment * (1 - (1 + r) ** (-periods)) / r
    if is_beginning:
        pv_annuity *= (1 + r)
print(f"Present value of the payments = {pv_annuity:,.2f}")
How to write it in LaTeX and other math languages (copy and paste)
PV = FV / (1 + r)ᴺ
PV = \dfrac{FV}{(1+r)^{N}}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <mi>PV</mi>
    <mo>=</mo>
    <mfrac>
      <mi>FV</mi>
      <msup>
        <mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>r</mi><mo>)</mo></mrow>
        <mi>N</mi>
      </msup>
    </mfrac>
  </mrow>
</math>
PV = FV / (1+r)^N
pv = fv/(1 + r)^n
pv := fv/(1 + r)^n;
pv = fv/(1 + r)^n;
PV = FV/(1+r)^N
PV = PMT × (1 − (1 + r)⁻ᴺ) / r
PV = PMT \cdot \dfrac{1-(1+r)^{-N}}{r}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
<mrow>
<mi>PV</mi>
<mo>=</mo>
<mi>PMT</mi>
<mo>⋅</mo>
<mfrac>
<mrow>
<mn>1</mn>
<mo>−</mo>
<msup>
<mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>r</mi><mo>)</mo></mrow>
<mrow><mo>−</mo><mi>N</mi></mrow>
</msup>
</mrow>
<mi>r</mi>
</mfrac>
</mrow>
</math>
PV = PMT (1 - (1+r)^(-N)) / r
pv = pmt (1 - (1 + r)^(-n))/r
pv := pmt*(1 - (1 + r)^(-n))/r;
pv = pmt*(1 - (1 + r)^(-n))/r;
PV = PMT(1-(1+r)^(-N))/r
PV = PMT × (1 − (1 + r)⁻ᴺ) / r × (1 + r)
PV = PMT \cdot \dfrac{1-(1+r)^{-N}}{r} \cdot (1+r)
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
<mrow>
<mi>PV</mi>
<mo>=</mo>
<mi>PMT</mi>
<mo>⋅</mo>
<mfrac>
<mrow>
<mn>1</mn>
<mo>−</mo>
<msup>
<mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>r</mi><mo>)</mo></mrow>
<mrow><mo>−</mo><mi>N</mi></mrow>
</msup>
</mrow>
<mi>r</mi>
</mfrac>
<mo>⋅</mo>
<mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>r</mi><mo>)</mo></mrow>
</mrow>
</math>
PV = PMT (1 - (1+r)^(-N)) / r * (1+r)
pv = pmt (1 - (1 + r)^(-n))/r (1 + r)
pv := pmt*(1 - (1 + r)^(-n))/r*(1 + r);
pv = pmt*(1 - (1 + r)^(-n))/r*(1 + r);
PV = PMT(1-(1+r)^(-N))/r (1+r)
How to have ChatGPT do the calculation
You are a present value calculation assistant. Do the following calculation by actually running Python code, and base your answer only on the numbers from the execution result (do not answer by mental math or guessing).

The rate is a constant 6% per period (r = 0.06).
Find each of the following:
1. The present value of $1,000 received in 10 years: PV = FV / (1+r)^N
2. The amount of the discount (FV − PV)
3. The present value of receiving $100 every year for 10 years, at the end of each year: PV = PMT × (1 − (1+r)^(−N)) / r

Show the formulas you used and the numbers from the execution result.
How to Use
-
1Enter your numbersType the numbers you want to calculate with into the input fields
-
2CalculatePress the "Calculate" button
-
3Check the resultThe result appears on the spot. The same page also explains the idea behind the calculation and the formula
DataChef Features

No technical knowledge required.
Intuitive and user-friendly operation.
Can be used without registering personal information.
Automatic file deletion by clicking "download".
and rapid file conversion.
No attribution required.
No need to contact us for commercial use permission.
Related Features
TVM Calculator (Time Value of Money Finance Calculator)
The all-in-one version that solves any of N, I/Y, PV, PMT and FV. It uses the same sign convention as a financial calculator
Compound Interest Calculator (Final Amount and Rate Conversion)
The exact reverse of discounting. How compound interest grows money now into money later
Interest Calculator (Savings Growth with Regular Contributions)
Finds your balance with compound interest plus monthly or yearly contributions. Also handles tax on interest and inflation
Future Value Calculator (Compound Growth with Regular Deposits)
The mirror image of this page. Finds how much money now plus regular deposits will grow to in the future