Choose how to enter the cash flows (fixed or irregular), then enter the initial investment and the cash flows. You get how many years it takes to get the investment back (payback period), plus the discounted payback period and the cash flow return rate, which account for the time value of money.
Table of Contents
-
What you can do on this page
-
What is this calculation used for?
-
How to Use
-
Formulas and graphs
-
Symbols and terms
-
Good to know before you start
-
How to calculate it in Excel
-
How to calculate it in Google Sheets
-
How to calculate it in Python
-
How to write it in LaTeX and other math languages (copy and paste)
-
How to have ChatGPT do the calculation
-
DataChef Features
-
Related Features
-
NumberChef Calculators List
What you can do on this page
- From the initial investment and the first-year cash flow (the money you receive that year), find the payback period: how many years it takes to get the initial investment back
- Works whether the cash flow is the same every year or grows or shrinks by a set percentage each year (fixed cash flow mode)
- If the amounts differ from year to year, enter them one year at a time (irregular cash flow mode, up to 20 years)
- Enter a discount rate to also get the discounted payback period, which accounts for the time value of money. The cash flow return rate (the yearly rate, same as IRR) is calculated whatever the discount rate
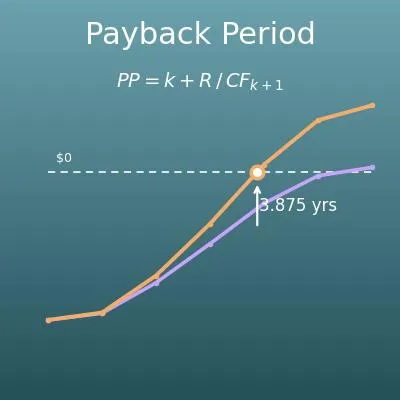
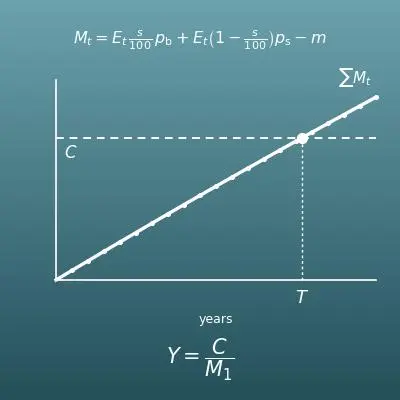
- Also shows a year-by-year table (cumulative cash flow, before and after discounting) and a graph of the point where the cumulative cash flow crosses the $0 line
What is this calculation used for?
"A $400,000 machine will cut costs by $150,000 a year." The payback period is \(400{,}000 \div 150{,}000 \approx 2.7\) years. Many companies set an internal rule such as "approve if it pays back within 3 years", and the payback period is the first test a proposal must pass. It is a standard argument not only for finance and planning teams but also when people on the shop floor propose new equipment.
Future cash flows are only estimates, so a good practice is to also calculate with conservative numbers.
If a home solar system costs $20,000 and saves $2,000 a year on electric bills, the payback period is \(20{,}000 \div 2{,}000 = 10\) years. Solar panels are said to last 25 to 30 years, so a key question is whether the payback period is well within that lifetime. Insulation, a heat pump or a high-efficiency water heater can be compared the same way.
Electricity prices and bill credits change over time, so try entering a rate of change to see how much a change in these assumptions matters.
When opening a restaurant or a franchise, "how many years to earn back the startup costs" is a central number in the business plan. For example, with $500,000 in startup costs and $125,000 a year in expected cash flow (what is left of sales after expenses), the payback period is 4 years.
Right after opening it is hard to predict how many customers will come, so the irregular mode helps: you can enter a smaller amount for year 1 and larger amounts from year 2 onward.
For business software or automation tools, turning the benefit into a payback period makes the decision easier: "$60,000 to set up, saves $30,000 a year in staff time, so the payback period is 2 years." Technology changes quickly and a tool may not stay in use for long, so a fast payback directly means lower risk.
This way of thinking is also common in the business case you write when asking for budget approval.
The strength of the payback period is that it sums up "how short the uncertain period is" in a single number. In industries where technology and trends change quickly, estimates for the distant future are unreliable, so a fast payback is valued.
On the other hand, the payback period has well-known weaknesses: it ignores the money earned after the payback, and it ignores the time value of money. An investment that pays back in 5 years and then keeps earning for 10 more years loses to one that pays back in 3 years and then ends. That is why, in practice, the standard approach is to combine it with the discounted payback period, NPV and IRR.
Formulas and graphs
Symbols and terms
Symbols
| \(PP\) | P P (payback period) | Payback period. The number of years until the initial investment comes back, that is, until the cumulative net cash flow reaches $0. (Example - a $100,000 investment that returns $20,000 every year has a payback period of 5 years) |
| \(DPP\) | D P P (discounted payback period) | Discounted payback period. The payback period counted after turning future money into its value today with the discount rate. It is always longer than the ordinary payback period. |
| \(I\) | I | The initial investment, the money paid at the start. In this calculator you enter it as a positive amount, and it is treated internally as a negative outflow in year 0. |
| \(CF\), \(CF_n\) | C F, C F sub n | Cash flow, the money received in a year. \(CF_n\) is the cash flow in year \(n\). A negative value is an extra expense in that year. |
| \(DCF_n\) | D C F sub n | Discounted cash flow in year \(n\). The money in year \(n\) converted to its value today. |
| \(g\) | g | The yearly rate of change of the cash flow. If it grows 5% every year, \(g=0.05\), and each year's amount is \((1+g)\) times the year before. |
| \(r\) | r | The discount rate, the yearly rate used to turn future money into its value today. The borrowing rate or a target rate of return is commonly used. |
| \(n\) | n | The number of years passed (which year it is). The time of the investment counts as year 0. |
| \(k\) | k | The full years before payback, the last year in which the cumulative net cash flow is still negative. |
| \(R\) | capital R | The amount still to recover at the end of year \(k\), the part of the initial investment that has not come back yet. |
| \(\ln\) | L N, natural log | The natural logarithm. It tells you what power of \(e\) (about 2.718) gives the number. You can find it with the ln key on a scientific calculator or the LN function in Excel. It appears in the closed-form formula for the discounted payback period. |
Terms
| payback period | The time it takes to get the initial investment back. The shorter it is, the sooner you earn back your money and the shorter the uncertain period, so the risk is considered lower. Judging investment options by how short their payback is is called the payback method. |
| break-even point | The point where gains and losses exactly balance. The payback period is the time it takes for the cumulative cash flow to reach the break-even point ($0). |
| cash flow | Money coming in and going out. Money received is a positive number and money paid is a negative number. For the payback period, what matters is when and how much comes in. |
| cumulative net cash flow | The total money received so far minus the initial investment. The moment it turns from negative to positive is the moment of payback. |
| discount rate | The yearly rate used to turn future money into its value today (to discount it). For example, $11,000 one year from now, discounted at 10% a year, is worth $10,000 today. |
| DCF (discounted cash flow) | A future cash flow converted to its value today with the discount rate. It is also the basis of the DCF method, a standard way to value companies and real estate. |
| discounted payback period | The payback period counted with the cumulative discounted cash flow. Because it accounts for the time value of money, it is always longer than the ordinary payback period, and with a high discount rate the investment may never be paid back. |
| linear interpolation | A way to find a value between two points by treating the line between them as straight. For the payback period, it assumes the next year's money comes in evenly over the year and finds the payback point within the year proportionally. |
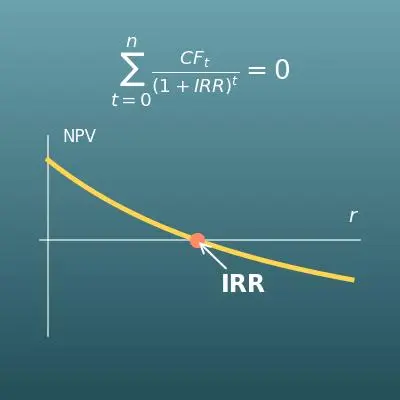
| cash flow return rate | The yearly rate of return that all the cash flows of the investment add up to. It is the same calculation as the IRR (internal rate of return). It shows not only how fast you are paid back but also how much you earn, in a single number. |
| natural logarithm | The logarithm with base \(e\) (about 2.718). \(\ln x\) tells you what power of \(e\) gives \(x\). It is taught in high school precalculus, but a calculator or Excel can do the arithmetic for you. |
Good to know before you start
Here is what helps you use the calculation on this page with real understanding, not just by pressing the button.
| Percents (Grade 6) |
|
| Positive and negative numbers (Grades 6–7) |
|
| Exponents (Grade 8) |
|
| Exponential functions and logarithms (Algebra 2) |
|
| Compound interest and the time value of money (high school personal finance and math) |
|
How to calculate it in Excel
| Initial investment ($) | 100000 |
| Cash flow per year ($) | 30000 |
| Payback period (years) | =B1/B2 |
| Cash flow in year 1 ($) | 30000 |
| Rate of change (%; enter a decline as negative) | 5 |
| Year n | 3 |
| Cash flow in year n ($) | =B1*(1+B2/100)^(B3-1) |
| Money received in year n ($) | 12100 |
| Discount rate (%) | 10 |
| Years passed n | 2 |
| Discounted cash flow ($) | =B1/(1+B2/100)^B3 |
| Full years before payback k | 3 |
| Still to recover R ($) | 3500 |
| Cash flow in the next year ($) | 4000 |
| Payback period (years) | =B1+B2/B3 |
| Initial investment ($) | 100000 |
| Cash flow per year ($) | 30000 |
| Discount rate (%) | 10 |
| Discounted payback period (years) | =-LN(1-B1*B3/100/B2)/LN(1+B3/100) |
The fourth table is the case where $3,500 is left to recover after year 3 and $4,000 comes in during year 4: 3 + 3500 ÷ 4000 = 3.875 years.
The fifth table is the closed-form formula with the LN function (natural log), which gives about 4.254 years. Just replace the numbers in column B with your own.
How to calculate it in Google Sheets
| Initial investment ($) | 100000 |
| Cash flow per year ($) | 30000 |
| Payback period (years) | =B1/B2 |
| Cash flow in year 1 ($) | 30000 |
| Rate of change (%; enter a decline as negative) | 5 |
| Year n | 3 |
| Cash flow in year n ($) | =B1*(1+B2/100)^(B3-1) |
| Money received in year n ($) | 12100 |
| Discount rate (%) | 10 |
| Years passed n | 2 |
| Discounted cash flow ($) | =B1/(1+B2/100)^B3 |
| Full years before payback k | 3 |
| Still to recover R ($) | 3500 |
| Cash flow in the next year ($) | 4000 |
| Payback period (years) | =B1+B2/B3 |
| Initial investment ($) | 100000 |
| Cash flow per year ($) | 30000 |
| Discount rate (%) | 10 |
| Discounted payback period (years) | =-LN(1-B1*B3/100/B2)/LN(1+B3/100) |
How to calculate it in Python
initial_investment = 100000                    # initial investment ($)
discount_rate = 0.10                           # discount rate (per year; 10% is 0.10)
cash_flows = [5000, 25000, 35000, 40000, 30000, 10000]   # cash flow for each year from year 1 ($)

# Payback period: find the point within the year where the cumulative net cash flow crosses $0, by linear interpolation
def payback_period(investment, cfs):
    cumulative = -investment
    for year, cf in enumerate(cfs, start=1):
        previous = cumulative
        cumulative += cf
        if previous < 0 and cumulative >= 0:
            return (year - 1) + (-previous) / cf
    return None   # not paid back within the years entered

# Discounted payback period: convert each year's money to today's value first, then do the same
def discounted_payback_period(investment, cfs, rate):
    cumulative = -investment
    for year, cf in enumerate(cfs, start=1):
        previous = cumulative
        discounted_cf = cf / (1 + rate) ** year
        cumulative += discounted_cf
        if previous < 0 and cumulative >= 0:
            return (year - 1) + (-previous) / discounted_cf
    return None

pp = payback_period(initial_investment, cash_flows)
dpp = discounted_payback_period(initial_investment, cash_flows, discount_rate)
print(f"Payback period: {pp:.3f} years")
print(f"Discounted payback period: {dpp:.3f} years")
How to write it in LaTeX and other math languages (copy and paste)
PP = I ÷ CF
PP = \dfrac{I}{CF}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <mi>PP</mi>
    <mo>=</mo>
    <mfrac>
      <mi>I</mi>
      <mi>CF</mi>
    </mfrac>
  </mrow>
</math>
PP = I / (CF)
invest/cf
PP := invest/cf;
PP = invest/cf;
PP = I/CF
CFₙ = CF₁ × (1 ± g)ⁿ⁻¹
CF_n = CF_1 \times (1 \pm g)^{n-1}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
<mrow>
<msub><mi>CF</mi><mi>n</mi></msub>
<mo>=</mo>
<msub><mi>CF</mi><mn>1</mn></msub>
<mo>×</mo>
<msup>
<mrow><mo>(</mo><mn>1</mn><mo>±</mo><mi>g</mi><mo>)</mo></mrow>
<mrow><mi>n</mi><mo>−</mo><mn>1</mn></mrow>
</msup>
</mrow>
</math>
CF_n = CF_1 (1 +- g)^(n-1)
cf1*(1 + g)^(n - 1)
cfn := cf1*(1 + g)^(n - 1);
cfn = cf1*(1 + g)^(n - 1);
CF_n = CF_1 (1 ± g)^(n−1)
DCFₙ = CFₙ ÷ (1 + r)ⁿ
DCF_n = \dfrac{CF_n}{(1+r)^{n}}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <msub><mi>DCF</mi><mi>n</mi></msub>
    <mo>=</mo>
    <mfrac>
      <msub><mi>CF</mi><mi>n</mi></msub>
      <msup>
        <mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>r</mi><mo>)</mo></mrow>
        <mi>n</mi>
      </msup>
    </mfrac>
  </mrow>
</math>
DCF_n = (CF_n) / ((1 + r)^n)
cfn/(1 + r)^n
DCFn := cfn/(1 + r)^n;
dcfn = cfn/(1 + r)^n;
DCF_n = CF_n/(1 + r)^n
PP = k + R ÷ CFₖ₊₁
PP = k + \dfrac{R}{CF_{k+1}}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
  <mrow>
    <mi>PP</mi>
    <mo>=</mo>
    <mi>k</mi>
    <mo>+</mo>
    <mfrac>
      <mi>R</mi>
      <msub><mi>CF</mi><mrow><mi>k</mi><mo>+</mo><mn>1</mn></mrow></msub>
    </mfrac>
  </mrow>
</math>
PP = k + R / (CF_(k+1))
k + rem/cfnext
PP := k + rem/cfnext;
PP = k + rem/cfnext;
PP = k + R/CF_(k+1)
DPP = −ln(1 − I × r ÷ CF) ÷ ln(1 + r)
DPP = \dfrac{-\ln\left(1 - \dfrac{I \times r}{CF}\right)}{\ln(1+r)}
<math xmlns="http://www.w3.org/1998/Math/MathML" display="block">
<mrow>
<mi>DPP</mi>
<mo>=</mo>
<mfrac>
<mrow>
<mo>−</mo>
<mi>ln</mi>
<mrow>
<mo>(</mo>
<mn>1</mn>
<mo>−</mo>
<mfrac>
<mrow><mi>I</mi><mo>×</mo><mi>r</mi></mrow>
<mi>CF</mi>
</mfrac>
<mo>)</mo>
</mrow>
</mrow>
<mrow>
<mi>ln</mi>
<mrow><mo>(</mo><mn>1</mn><mo>+</mo><mi>r</mi><mo>)</mo></mrow>
</mrow>
</mfrac>
</mrow>
</math>
DPP = (-ln(1 - (I r) / (CF))) / (ln(1 + r))
-Log[1 - invest*r/cf]/Log[1 + r]
DPP := -ln(1 - invest*r/cf)/ln(1 + r);
DPP = -log(1 - invest*r/cf)/log(1 + r);
DPP = −ln(1 − I r/CF)/ln(1 + r)
How to have ChatGPT do the calculation
You are an investment calculation assistant. Do the following calculation by actually running Python code, and base your answer only on the numbers from the execution result (do not answer by mental math or guessing).

I invest $100,000 and receive these cash flows, starting in year 1: $5,000, $25,000, $35,000, $40,000, $30,000 and $10,000. The discount rate is 10% per year.
Find each of the following:
1. The payback period (years, 3 decimal places) = the point where the cumulative net cash flow reaches $0 (linear interpolation between the two points where the sign changes)
2. The discounted payback period (years, 3 decimal places) = the point found the same way after dividing each year's cash flow by (1 + 0.1)^(year number)
3. The cash flow return rate (%, 2 decimal places) = the IRR (internal rate of return) of the series (year 0 = -100000, years 1–6 = the amounts above)

Show the formulas you used and the numbers from the execution result.
How to Use
-
1Enter your numbersType the numbers you want to calculate with into the input fields
-
2CalculatePress the "Calculate" button
-
3Check the resultThe result appears on the spot. The same page also explains the idea behind the calculation and the formula
DataChef Features

No technical knowledge required.
Intuitive and user-friendly operation.
Can be used without registering personal information.
Automatic file deletion by clicking "download".
and rapid file conversion.
No attribution required.
No need to contact us for commercial use permission.
Related Features
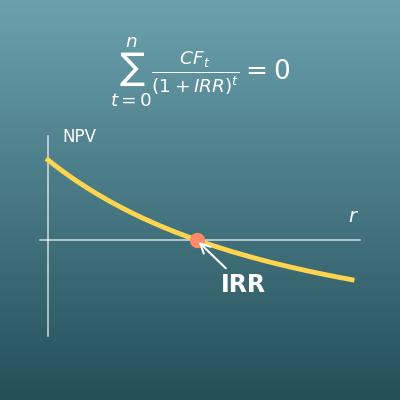
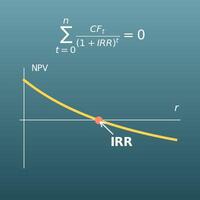
IRR Calculator (Internal Rate of Return from Cash Flows)
Finds the yearly rate of return from the same year-by-year cash flows. The standard measure used together with the payback period
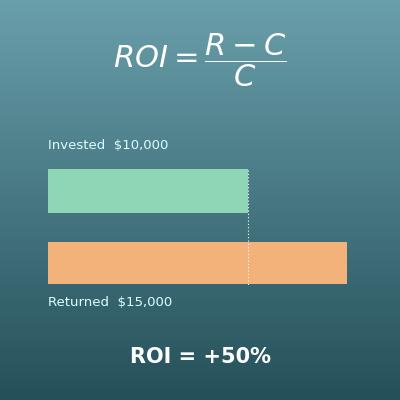
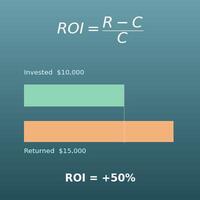
ROI Calculator (Return on Investment and Annualized ROI)
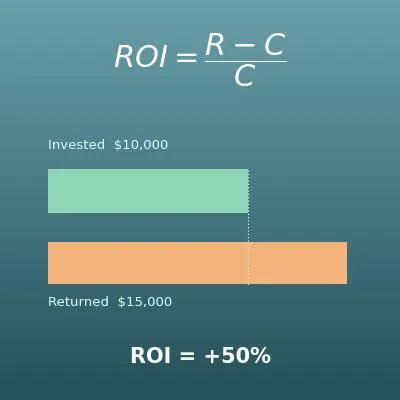
Finds ROI and annualized ROI from the amount invested and the amount returned. Easier for a simple investment that pays back all at once
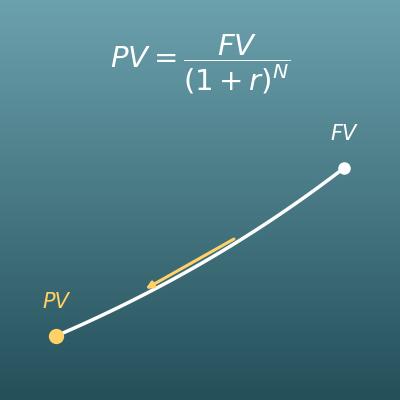
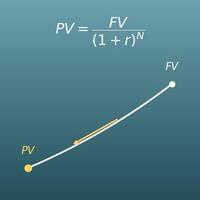
Present Value Calculator (Discounting and Present Value of an Annuity)
Discounting - turning future money into its value today. Learn the idea behind the discounted payback period here
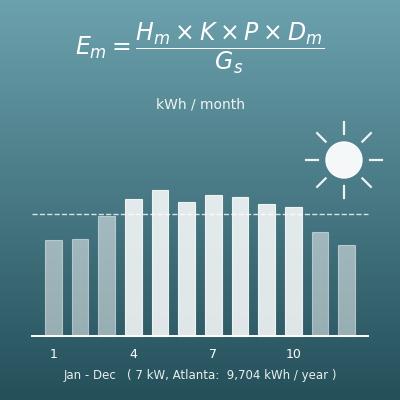
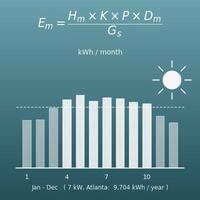
Solar Panel Output Calculator (Monthly and Annual kWh from System Size, Peak Sun Hours, Direction and Tilt)
Estimates monthly and annual solar output (kWh) and yearly output per kW from system size, local sunlight, panel direction and tilt, and system losses